By the time dessert arrived at my daughter Lily’s eighth birthday dinner, I already regretted inviting my husband’s family.
I had reserved a private room at a steakhouse in Columbus, Ohio. I paid the deposit, ordered the cake, and covered the entire bill because my husband, Daniel, had been out of work for two months.
Paying was not the problem.
The problem was watching my mother-in-law, Carol, behave as though everything I paid for automatically belonged to her.
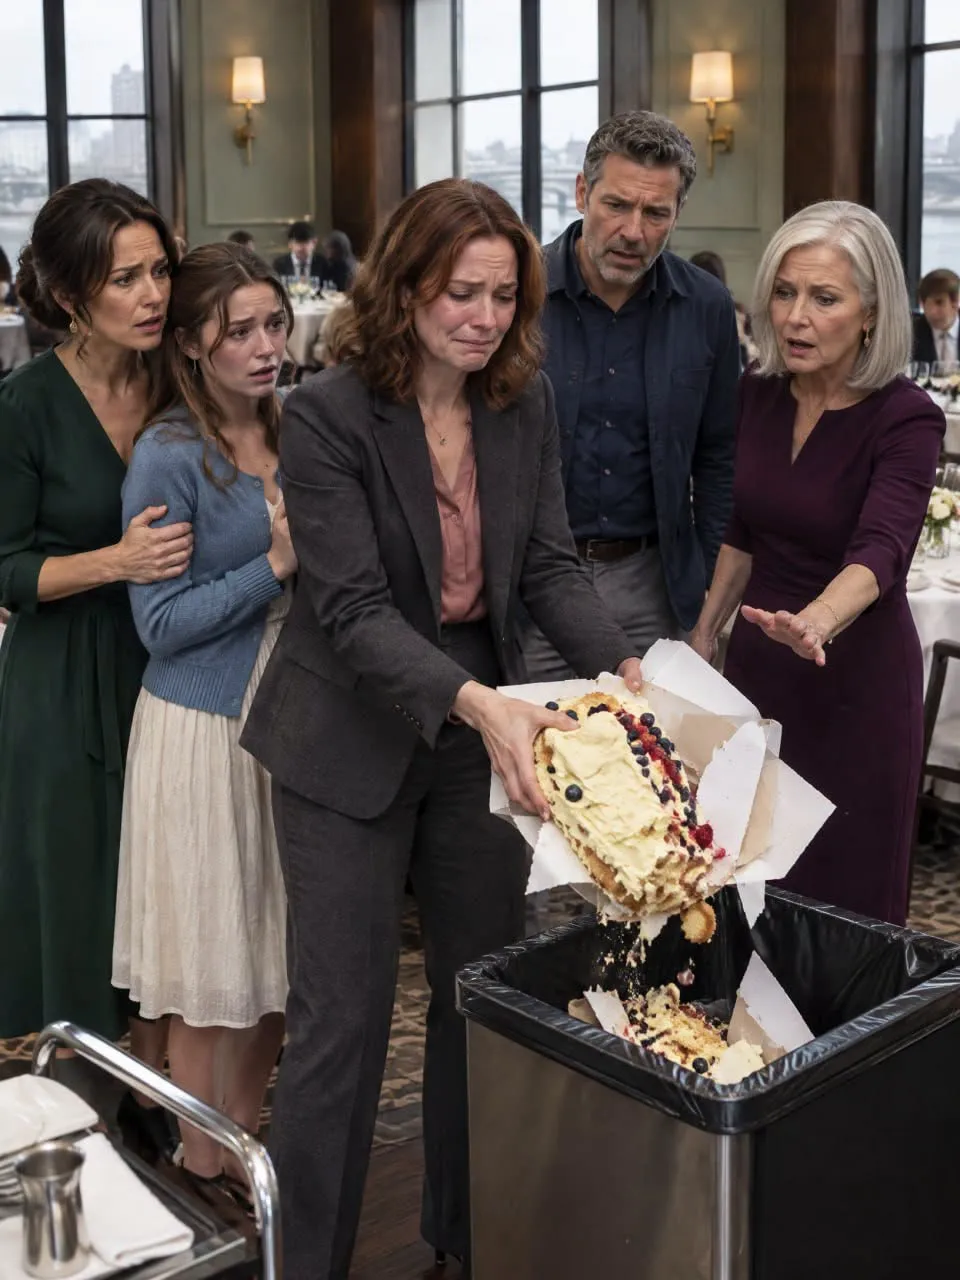
The server had barely cleared the plates when Carol began filling takeout boxes with rolls, steak, vegetables, and nearly half of Lily’s birthday cake.
“Leave some cake,” I told her. “Lily wants some tomorrow.”
Carol barely looked at me.
“You have enough food at home.”
“I paid for this dinner,” I replied.
That finally got her attention.
“So now you’re keeping score?”
Daniel stared at his phone while his sister, Megan, sat quietly watching.
When I reached for the cake box, Carol raised her hand toward me in a gesture that immediately made me uncomfortable.
“Don’t you dare embarrass me in front of my family.”
The room went silent.
Lily froze beside me.
At that point, I was finished arguing.
I took the boxes, walked to the trash, and threw the remaining food away.
“There,” I said. “Now nobody takes it.”
Daniel finally reacted.
“What is wrong with you?”
I picked up Lily’s coat.
“What’s wrong is that your mother just raised her hand toward me in front of our daughter, and you sat there watching.”
Carol called me dramatic. Megan called me selfish. Daniel ordered me to sit down.
I didn’t.
I took Lily, left the restaurant, packed overnight bags, and stayed with my friend Jenna.
I thought the birthday dinner had been bad.
The next morning showed me how much worse things actually were.
The Bank Called at 8:17 A.M.
Lily was eating cereal at Jenna’s kitchen counter when my phone rang.
The caller identified himself as a loan officer from First Federal Bank.
He wanted to confirm whether I was still willing to act as a personal guarantor on a $48,000 business loan for Megan.
I nearly dropped the phone.
“I never agreed to guarantee anything.”
There was a pause.
Then he carefully explained that my name, income information, employer details, and partial Social Security number had been submitted with the application.
Suddenly I remembered something.
Three nights earlier, Daniel had asked me to send him a picture of my latest pay stub. He claimed our apartment complex needed updated income verification.
I had sent it without thinking twice.
I immediately asked the bank to stop the application and send me whatever information they were legally allowed to provide.
Then I called Daniel.
“Did you put my information on Megan’s loan application?”
Silence.
Not confusion.
Not surprise.
Just silence.
Finally, he sighed.
“It wasn’t supposed to be a big deal.”
I stepped into Jenna’s laundry room so Lily could not hear me.
“You used my pay stub.”
“I gave Megan the numbers,” he replied. “The bank still has to approve everything.”
“That is not an answer.”
Then the truth started coming out.
Megan wanted to open a salon. Carol had already invested $15,000, but Megan’s credit was not strong enough to qualify for the loan alone.
Daniel was unemployed.
I was the only person with steady income.
“So you volunteered me?” I asked.
“We’re married, Rachel.”
“That doesn’t make my signature yours.”
Daniel insisted nobody had forged my signature. According to him, the bank was simply calling to confirm everything and I could have agreed.
Then he said something that erased any doubt about how he viewed the situation.
“After what you pulled last night, you owe my family some goodwill.”
I hung up.
Then I Checked Our Savings
Within an hour, the bank emailed me documents showing that I had been listed as a proposed guarantor.
My signature line was blank, but my employment information, salary, address, and partial Social Security number were already there.
Jenna looked through the paperwork.
“You need to lock your credit.”
I froze my credit files, changed the passwords on my financial accounts, and contacted my employer.
Then I checked our joint savings.
That was when the birthday dinner stopped being my biggest concern.
Four days earlier, Daniel had transferred $6,500 from our savings into his personal account.
The memo said:
Family investment.
That money was supposed to help pay for Lily’s summer care, emergencies, and eventually a security deposit on a better apartment.
I called Daniel again.
“Did you give Megan $6,500?”
“Mom said she was short.”
“You didn’t ask me.”
His answer stunned me.
“I knew what you’d say.”
That sentence told me everything.
“You knew I would say no, so you moved the money anyway.”
“It’s our money.”
“Then why did you transfer it into your private account first?”
He had no answer.
His Mother Started Blaming Me
By noon, Carol was sending angry messages.
She said I had humiliated her.
She accused me of destroying Megan’s future.
She insisted Daniel had every right to use marital money to help his sister.
Then she sent another message:
If you call the bank again and cause trouble, don’t expect this family to forgive you.
I took screenshots.
That afternoon, I met with a family-law attorney.
I was not ready to say my marriage was over.
I simply wanted to know how to protect myself if Daniel continued moving money and using my financial information without permission.
The attorney asked me one question:
“Do you know whether he has tried to open anything else using your information?”
I didn’t.
We checked my credit report.
There was the inquiry from First Federal.
But there was another inquiry from an online lender two weeks earlier.
Daniel had never told me about it.
That evening, I opened my own checking account and redirected my paycheck there. I left enough money in our joint account for rent, utilities, and Lily’s expenses.
Then Megan left me a voicemail.
She was crying.
Not because she was sorry.
Because the bank had stopped her loan.
“You ruined this for me,” she said. “I already signed a lease.”
That was the first time anyone had mentioned a lease.
They Had Already Committed the Money
Megan had signed a commercial lease for a salon suite before securing the financing she needed.
Carol had put in money.
Equipment had been ordered.
Rent was approaching.
The $48,000 loan was supposed to pay for renovations, salon chairs, sinks, inventory, insurance, and several months of operating expenses.
They had committed first and figured they would solve the financing problem afterward.
Apparently, I was supposed to be that solution.
Daniel came to Jenna’s house that evening.
He talked about how Megan could lose the lease and how Carol could lose the money she had already invested.
I listened.
Then I asked about the $6,500.
“I was going to put it back,” he said.
“With what money?”
“I’m interviewing.”
“That is not money.”
Then I asked about the second lender.
His expression changed.
Eventually, he admitted he had started another application using my income information because he wanted to see how much “we” might qualify for.
“You used my information twice?”
“I didn’t sign your name.”
“You keep saying that as though it makes this normal.”
He insisted he was trying to fix things.
“For Megan?” I asked.
“For all of us.”
I stared at him.
“How does putting $48,000 of your sister’s business debt on me help Lily and me?”
He had no answer.
Then he said the sentence that made everything perfectly clear.
“Mom said you’d say no if we asked first.”
There it was.
This was not a misunderstanding.
They expected me to refuse.
So instead of asking, they decided to move forward first and pressure me afterward.
Daniel asked me to reconsider.
He said Megan could eventually refinance and remove me from the loan.
“No.”
“You don’t even know the business plan.”
“No.”
“Can you stop saying no for five seconds?”
“No.”
Then I asked him to leave.
The Bank Closed the Application
The following morning, the bank’s fraud and compliance department contacted me.
They had spoken with Megan and closed the application. They also explained how I could dispute the credit inquiry.
Later, Megan emailed me.
At first, she claimed Daniel had told her I was “basically on board.”
Then she admitted something much more important.
She wrote that Daniel believed it would be easier for me to accept the loan after the application was already moving forward.
I saved the email and sent a copy to my attorney.
Carol called again from another number.
She returned to arguing about the birthday dinner and accused me of wasting food just to hurt her.
That was when I finally understood why she kept bringing up the leftovers.
If the argument was about cake, she could call me petty.
If it was about food, she could call me wasteful.
If it was about the dinner, she could pretend she was the victim.
But this was never really about leftovers.
“This is not about the food,” I told her.
“You raised your hand toward me in front of my daughter. Then the next morning I discovered my personal information had been placed on Megan’s loan application.”
Carol went quiet.
Then she said:
“Families help each other.”
“That answer tells me everything I need to know.”
I hung up.
Two days later, the $6,500 appeared back in our joint account.
But the damage had already been done.
For days, Daniel tried to convince me that Megan would repay the loan, that the salon would succeed, and that I probably would never lose any money.
Every argument ignored the same basic fact.
I had never agreed to any of it.
Eventually, Daniel and I met with attorneys and began discussing a separation.
The strangest part was realizing that the disaster had started with something as small as leftover birthday cake.
That night, I thought I was fighting with my mother-in-law over food.
By the next morning, I realized I was actually fighting for control over my money, my identity, and my ability to say no.
Carol had been determined to take home everything she believed the family was entitled to.
I just never imagined that included my credit, my savings, and my name.
Related Articles
Wealthy Woman Refused to Leave One Turkey for a Sick Boy — Then Her Father Walked Into the Store
I Farmed Beside My Dad for 22 Years, but He Left All 400 Acres to My Brother — Then Planting Season Changed Everything
My Husband Had a Vasectomy, but Two Months Later, I Found Out I Was Pregnant